IRS Innocent Spouse Relief in Waco, TX
When an ex-spouse or estranged partner conceals income, claims invalid deductions, or leaves joint taxes unpaid, you should not bear their financial burden. Learn how federal relief under 26 U.S.C. § 6015 breaks joint liability under Texas community property rules.
Federal authority granting complete relief from joint tax balances.
Official IRS request for traditional, separation, or equitable relief.
Federal law freezes IRS levy actions during claim review.
Relief for separated Texas spouses filing separate returns.
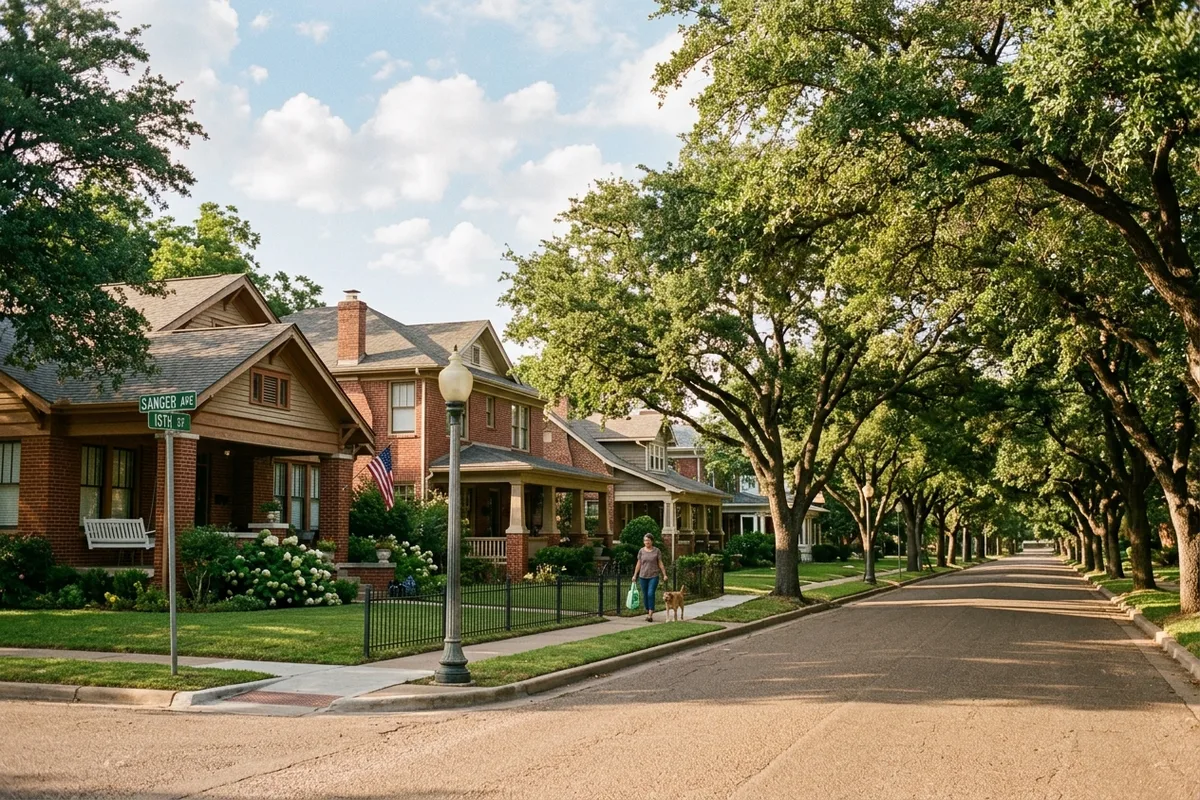
Protecting Waco Family Homes & Community Assets
Historic residential avenues across Sanger-Heights, Castle Heights, and Austin Avenue
The Community Property Trap: Joint Liability vs. Texas Family Code
Texas is one of nine community property states. Under Texas Family Code § 3.002, all property acquired by either spouse during marriage is presumed to be community property. When married couples file a joint federal tax return, federal law under 26 U.S.C. § 6013(d)(3) creates strict joint and several liability:
100% Liability for Both Parties
The IRS does not divide the debt 50/50. They hold both partners 100% responsible for the full balance. If your ex-spouse fails to pay, hides assets, or leaves town, the IRS will pursue you for the entire tax, civil fraud penalties, and accumulated statutory interest.
Sole vs. Joint Management Property
Texas law distinguishes between sole-management community property (e.g., your personal wages, separate bank account) and joint community property. However, once you sign a joint return, the federal tax code pierces state protections unless you invoke IRC § 6015.
Three Statutory Avenues to Innocent Spouse Relief Under IRC § 6015
Congress enacted 26 U.S.C. § 6015 to provide three distinct statutory relief mechanisms, each designed for specific factual scenarios:
1. Traditional Innocent Spouse Relief (26 U.S.C. § 6015(b))
Understatement DefenseApplies when a joint return understated the correct tax liability because of your spouse's "erroneous items"—such as unreported side income, undisclosed 1099 contracts, or fictitious business deductions. You must establish that when you signed the return, you did not know and had no reason to know of the understatement, and that taking into account all facts, holding you liable is inequitable.
2. Separation of Liability Relief (26 U.S.C. § 6015(c))
For Divorced / Separated SpousesAvailable if at the time of filing Form 8857, you are legally divorced, widowed, or have lived completely separate and apart from your spouse for at least 12 consecutive months. The IRS recomputes your tax deficiency as if you had filed separate returns, assigning each item to the spouse who earned or incurred it. Relief is barred only if the IRS proves you had actual knowledge of the erroneous item.
3. Equitable Relief (26 U.S.C. § 6015(f))
Underpayment & HardshipThe broadest and most flexible relief avenue. Unlike §§ 6015(b) and (c), Equitable Relief covers underpayment of tax—situations where the tax return was filed accurately, but your spouse failed to pay the balance due (e.g., your spouse promised to pay from business proceeds but did not). Evaluation factors under Revenue Procedure 2013-34 include marital status, economic hardship, domestic abuse, mental coercion, and who received the economic benefit of the unpaid funds.
Comparison: Innocent Spouse Relief Options at a Glance
Choosing the correct legal basis on Form 8857 is essential to securing an administrative grant from the IRS Cincinnati Innocent Spouse Operation:
| Relief Category | Statutory Authority | Core Eligibility Standard | Filing Deadline | Scope of Protection |
|---|---|---|---|---|
| Traditional Innocent Spouse Relief | 26 U.S.C. § 6015(b) | Understatement caused by spouse's erroneous items; requesting spouse had no knowledge or reason to know | Within 2 years of first IRS collection action | Full relief from tax deficiency, civil penalties, and accrued interest |
| Separation of Liability Relief | 26 U.S.C. § 6015(c) | Divorced, legally separated, or living apart for 12+ months; no actual knowledge of unreported items | Within 2 years of first IRS collection action | Allocates deficiency strictly to the spouse who earned the income |
| Equitable Relief | 26 U.S.C. § 6015(f) | Taking into account all facts, it would be unfair to hold the spouse liable; covers underpayments and deficiencies | Up to 10-year collection statute (CSED); 3 years for refunds | Relief based on domestic abuse, economic hardship, or marital deceit |
| Injured Spouse Allocation | 26 U.S.C. § 6402 / Form 8379 | Requesting spouse's portion of joint refund was intercepted for spouse's pre-existing individual debts | Within 3 years of return filing date | Protects and refunds your individual share of a joint tax refund |
Innocent Spouse (Form 8857) vs. Injured Spouse (Form 8379)
Taxpayers in Waco frequently confuse these two similar-sounding remedies. Understanding the legal difference avoids critical filing mistakes:
Innocent Spouse Relief
Used when the IRS says you owe money because your spouse failed to report income, claimed fraudulent write-offs, or neglected to pay the balance. You are asking to be permanently released from paying the tax.
Injured Spouse Allocation
Used when you filed a joint return that generated an expected refund, but the Department of the Treasury intercepted your refund to satisfy your spouse's past-due separate debts (e.g., Texas child support arrears, student loans, or prior individual tax debts). Form 8379 calculates and returns your share of the check.
Why McLennan County Divorce Decrees Don't Bind the IRS
One of the most devastating discoveries for Central Texas divorcees is that a state court divorce decree provides zero legal shield against IRS revenue officers.
Federal Supremacy Clause (U.S. Const. art. VI)
The IRS was not a party to your divorce proceedings in the McLennan County Courthouse. Under the Supremacy Clause of the United States Constitution, federal tax statutes override state court divorce judgments. If your ex-spouse refuses to honor the decree and pay the tax balance, the IRS will seize your wages, freeze your bank accounts, or file a Notice of Federal Tax Lien against your Waco property.
The Practitioner Solution: While you can sue your ex-spouse in state district court for contempt or breach of contract, that process takes months and does not stop IRS collection. Filing Form 8857 under 26 U.S.C. § 6015 triggers an immediate federal statutory injunction under § 6015(e)(1)(B), freezing IRS enforcement while your liability is legally dissolved.
Step-by-Step Filing Roadmap with a Licensed Circular 230 Practitioner
Winning Innocent Spouse Relief requires presenting structured documentary evidence that satisfies IRS Cincinnati examiners and surviving potential review before the U.S. Tax Court:
Step 1: Obtain Comprehensive Transcripts
A Circular 230 licensed CPA or Enrolled Agent files IRS Form 8821 to pull Account Transcripts and Wage & Income Transcripts across all affected years, determining the exact source and nature of the assessment.
Step 2: Document Lack of Knowledge & Coercion
Assemble financial records proving you did not participate in the spouse's business, had no access to separate bank accounts, or were subjected to financial control, deceit, or emotional duress.
Step 3: Submit Form 8857 Narrative Brief
Submit Form 8857 supported by an authoritative legal memorandum referencing Rev. Proc. 2013-34 tier criteria, establishing threshold eligibility and positive equitable factors.
Step 4: Statutory Collection Stay & Final Determination
Monitor the IRS collection hold under IRC § 6015(e)(1)(B). If the preliminary determination is adverse, a licensed representative can file an administrative appeal with the IRS Independent Office of Appeals or petition the United States Tax Court within 90 days.
Filing for relief under § 6015 is part of an integrated defense strategy. Review our complete resource for Texas tax relief and representation in Waco to understand how federal statutes safeguard community assets.
Facing Tax Debt Caused by an Ex-Spouse?
Talk directly with Maya, our automated voice assistant, or connect immediately with a Circular 230 licensed CPA or IRS Enrolled Agent serving Waco and McLennan County.
Frequently Asked Questions: Texas Innocent Spouse Relief
Does my McLennan County divorce decree protect me from the IRS?
No. Federal tax law under 26 U.S.C. § 6013(d)(3) supersedes Texas state court divorce decrees. Even if your 19th, 74th, 170th, or 414th District Court divorce decree assigns 100% of tax debt to your ex-spouse, the IRS is not bound by state court decrees and can legally seize your bank accounts or garnish wages unless you win formal federal relief under 26 U.S.C. § 6015.
What is the difference between an Injured Spouse and an Innocent Spouse?
An Innocent Spouse (Form 8857) seeks relief from a joint tax debt, penalty, or audit deficiency caused by a spouse's hidden income or false deductions. An Injured Spouse (Form 8379) seeks to recover their portion of a joint tax refund that was seized by the IRS to pay a spouse's separate past-due debt (such as past-due child support, prior-year individual taxes, or student loans).
How does Texas community property law affect separated spouses who file separate returns?
Under Texas Family Code § 3.002, income earned by either spouse during marriage is community property. If you file Married Filing Separately in Texas, federal law (IRC § 66) normally requires each spouse to report 50% of the combined community income. However, IRC § 66(c) provides innocent spouse relief from community property income allocation if your spouse did not notify you of the earnings.
Will the IRS notify my ex-spouse if I file for Innocent Spouse Relief?
Yes. By federal law (26 U.S.C. § 6015(h)(2)), the IRS is required to notify the non-requesting spouse and allow them to participate in the proceedings. However, the IRS protects your privacy: personal contact information, physical address, employer information, and domestic violence protective orders are strictly redacted from all materials shared with the ex-spouse.
Does filing Form 8857 stop IRS collection action in Waco?
Yes. Under 26 U.S.C. § 6015(e)(1)(B), the IRS is legally prohibited from initiating or continuing administrative collection actions (including bank levies and wage garnishments) while your request for Innocent Spouse Relief is pending evaluation before the IRS and during any subsequent appeal to the U.S. Tax Court.
Protect Your Income & Disconnect from Your Spouse's Tax Debt
Do not allow an ex-partner's unpaid taxes or concealed income to endanger your paycheck, bank accounts, or Waco home. Speak with a vetted, Circular 230 licensed CPA or IRS Enrolled Agent today.
Answered 24/7 · Connects with Circular 230 Licensed CPAs & IRS Enrolled Agents · No SSN Collected Online